
- expertise:
- CFD Trading, Forex, Derivatives, Risk Management
- credentials:
- Chartered ACII (2018) · Trading since 2012
- tested:
- 40+ forex & CFD platforms with live accounts
- expertise:
- Broker Comparison, ISA Strategy, Portfolio Management
- credentials:
- Active investor since 2013 · 11+ years experience
- tested:
- 40+ brokers with funded accounts
How We Test
Real accounts. Real money. Real trades. No demo accounts or press releases.
What we measure:
- Spreads vs advertised rates
- Execution speed and slippage
- Hidden fees (overnight, withdrawal, conversion)
- Actual withdrawal times
Scoring:
Fees (25%) · Platform (20%) · Assets (15%) · Mobile (15%) · Tools (10%) · Support (10%) · Regulation (5%)
Regulatory checks:
FCA Register verification · FSCS protection
Testing team:
Adam Woodhead (investing since 2013), Thomas Drury (Chartered ACII, 2018), Dom Farnell (investing since 2013) — 50+ platforms with funded accounts
Quarterly reviews · Corrections: in**@*******************co.uk
Disclaimer
Not financial advice. Educational content only. We're not FCA authorised. Consult a qualified advisor before investing.
Capital at risk. Investments can fall. Past performance doesn't guarantee future results.
CFD warning. 67-84% of retail accounts lose money trading CFDs. High risk due to leverage.
Contact: in**@*******************co.uk
Heading into 2026, compound interest remains most powerful when combined with time, reinvestment, and tax efficiency. With upcoming Cash ISA limit reductions from April 2027, UK investors have added incentive to prioritise Stocks & Shares ISAs and pensions for long-term compounding.
Quick Answer: Which Investments Give the Best Compound Interest?
The best compound interest investments in the UK include Stocks & Shares ISAs with index funds, pensions such as SIPPs, and ETFs. These market-based investments typically outpace inflation. Cash ISAs offer certainty but deliver weaker long-term growth, often failing to preserve purchasing power against inflation.
Platform Comparison
| Investment Provider | eToro | IG | XTB | Interactive Investor | Trading.com | Trading 212 |
|---|---|---|---|---|---|---|
| Regulator | FCA | FCA | FCA | FCA | FCA | FCA |
| Mobile App Usability | 5/5 | 4.5/5 | 4.4/5 | 4/5 | Not published | 4.5/5 |
| Variety of Assets | Stocks, cryptocurrencies, CFDs | 18,000+ markets, stocks, ETFs, commodities, currencies, bonds, funds | 9,100+ real stocks & ETFs, 2,600+ CFDs | 1,000+ ETFs, Stocks (UK & International), Bonds, Ethical Investments | Commission-free Investment Account (real shares) plus a separate CFD/forex account, 55 FX pairs | 20,000+ global stocks & ETFs, commodities, forex |
| ISA Available | Yes (in conjunction with Moneyfarm) | Yes | Yes (flexible) | Yes | Not published | Yes |
| Trustpilot Score | 4.3/5 | 4.0/5 | 4.4/5 | 4.7/5 | Not published | 4.6/5 |
| Fee Score | 4/5 | 4/5 | 4.3/5 | 4.2/5 | Not published | 4/5 |
| Overall Review Score | 4.7/5 | 4.5/5 | 4.6/5 | 4.4/5 | 3.9/5 (forex account score; investing account not separately rated) | 4.5/5 |
Welcome bonus for new UK clients — deposit & receive free shares. Stocks only, 90-day hold applies.
- Deposit £500 – £999Get £40
- Deposit £1k – £4,999Get £100
- Deposit £5k – £9,999Get £300
- Deposit £10,000+Get £500
Get up to £10,000 cashback on your first ISA deposit (min £500) or ISA transfer (£15,000+). Paid into your non-ISA balance.
- Bronze, Silver, Gold2% Cashback
- Platinum, Platinum+2.5% Cashback
- Diamond3% Cashback
CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 52% of retail investor accounts lose money when trading CFDs with this provider. You should consider whether you understand how CFDs work, and whether you can afford to take the high risk of losing your money.
eToro – Best for Beginners
- Fees & Spreads
- 3.8
- Platform & Tools
- 3.8
- Customer Service
- 3.7
- Ease of Use
- 4.8
- Mobile App
- 4.1

Pros
- Copy trading with CopyTrader™
- Commission-free stocks
- Simple, beginner-friendly interface
- Integrated crypto trading
Cons
- $5 withdrawal fee
- $10/month inactivity fee after 12 months
- Currency conversion fees apply
How Much Does It Cost to Invest with eToro?
eToro offers £0 commission on stocks. There's a $5 withdrawal fee and a $10 monthly inactivity fee after 12 months. Spreads on forex start from 1 pip. Currency conversion fees apply unless using eToro Money.
Is eToro Safe and FCA Regulated?
Yes, eToro is regulated by the FCA (FRN 583263) and protects UK client funds under FSCS. The platform also uses two-factor authentication and industry-standard security protocols.
Who Should Use eToro?
eToro is perfect for beginners who want a simple platform, low costs, and the ability to follow or copy expert investors. It also appeals to users exploring both stocks and crypto in one place.
What Features Stand Out on eToro's Platform?
eToro's standout feature is CopyTrader™, which lets users replicate the portfolios of top investors. The app also includes real-time data, social feeds, analyst ratings, and integrated crypto trading–all in an easy-to-navigate design.
IG – Diverse Instruments, Educational Resources, Competitive Pricing
- Fees & Spreads
- 4.2
- Platform & Tools
- 4.5
- Customer Service
- 3.8
- Ease of Use
- 4.1
- Mobile App
- 4.2
Pros
- Access to 18,000+ markets
- Advanced tools like ProRealTime
- ISA and SIPP available
- Strong FCA regulation
Cons
- £12/month inactivity fee
- Higher fees for infrequent traders
- May overwhelm beginners
How Much Does It Cost to Invest with IG?
UK share dealing costs £8 per trade or £3 if you make 3+ trades per month. Platform fees are £96/year unless actively waived. Forex spreads start from 0.6 pips. Additional charges apply for international markets and data feeds.
Is IG Safe and FCA Regulated?
Yes, IG is fully regulated by the Financial Conduct Authority (FCA). Client funds are held in segregated accounts and protected under the FSCS scheme up to £85,000 in case of broker insolvency.
Who Should Use IG?
IG is ideal for experienced investors who want access to global markets, powerful charting tools, and tax-efficient accounts. It suits active traders and long-term investors comfortable with a slightly more advanced platform.
What Features Stand Out on IG's Platform?
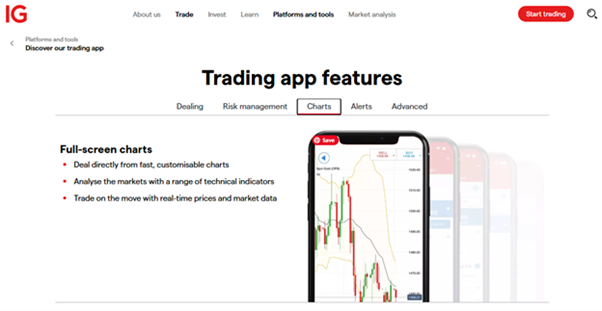
IG offers advanced charting, smart order types, ProRealTime integration, and extensive market research. Users can invest through web or mobile, with access to ISAs, SIPPs, and margin trading. The platform is customisable and supports multiple asset classes.
XTB – Compounding with 4% GBP Interest and Auto-Invest Plans
- Fees & Spreads
- 4.2
- Platform & Tools
- 4.4
- Customer Service
- 3.2
- Ease of Use
- 3.7
- Mobile App
- 3.3
Pros
- 4% interest on uninvested GBP funds, calculated daily and paid monthly
- Investment Plans auto-invest ETF portfolios with automatic payments
- Flexible Stocks and Shares ISA, free to open, keeps compounding tax-efficient
- Fractional investing across 9,100+ real stocks and ETFs
Cons
- 0.5% currency conversion cost on non-GBP stocks such as US shares
- 0.2% (min £10) commission above the EUR 100,000 monthly turnover threshold
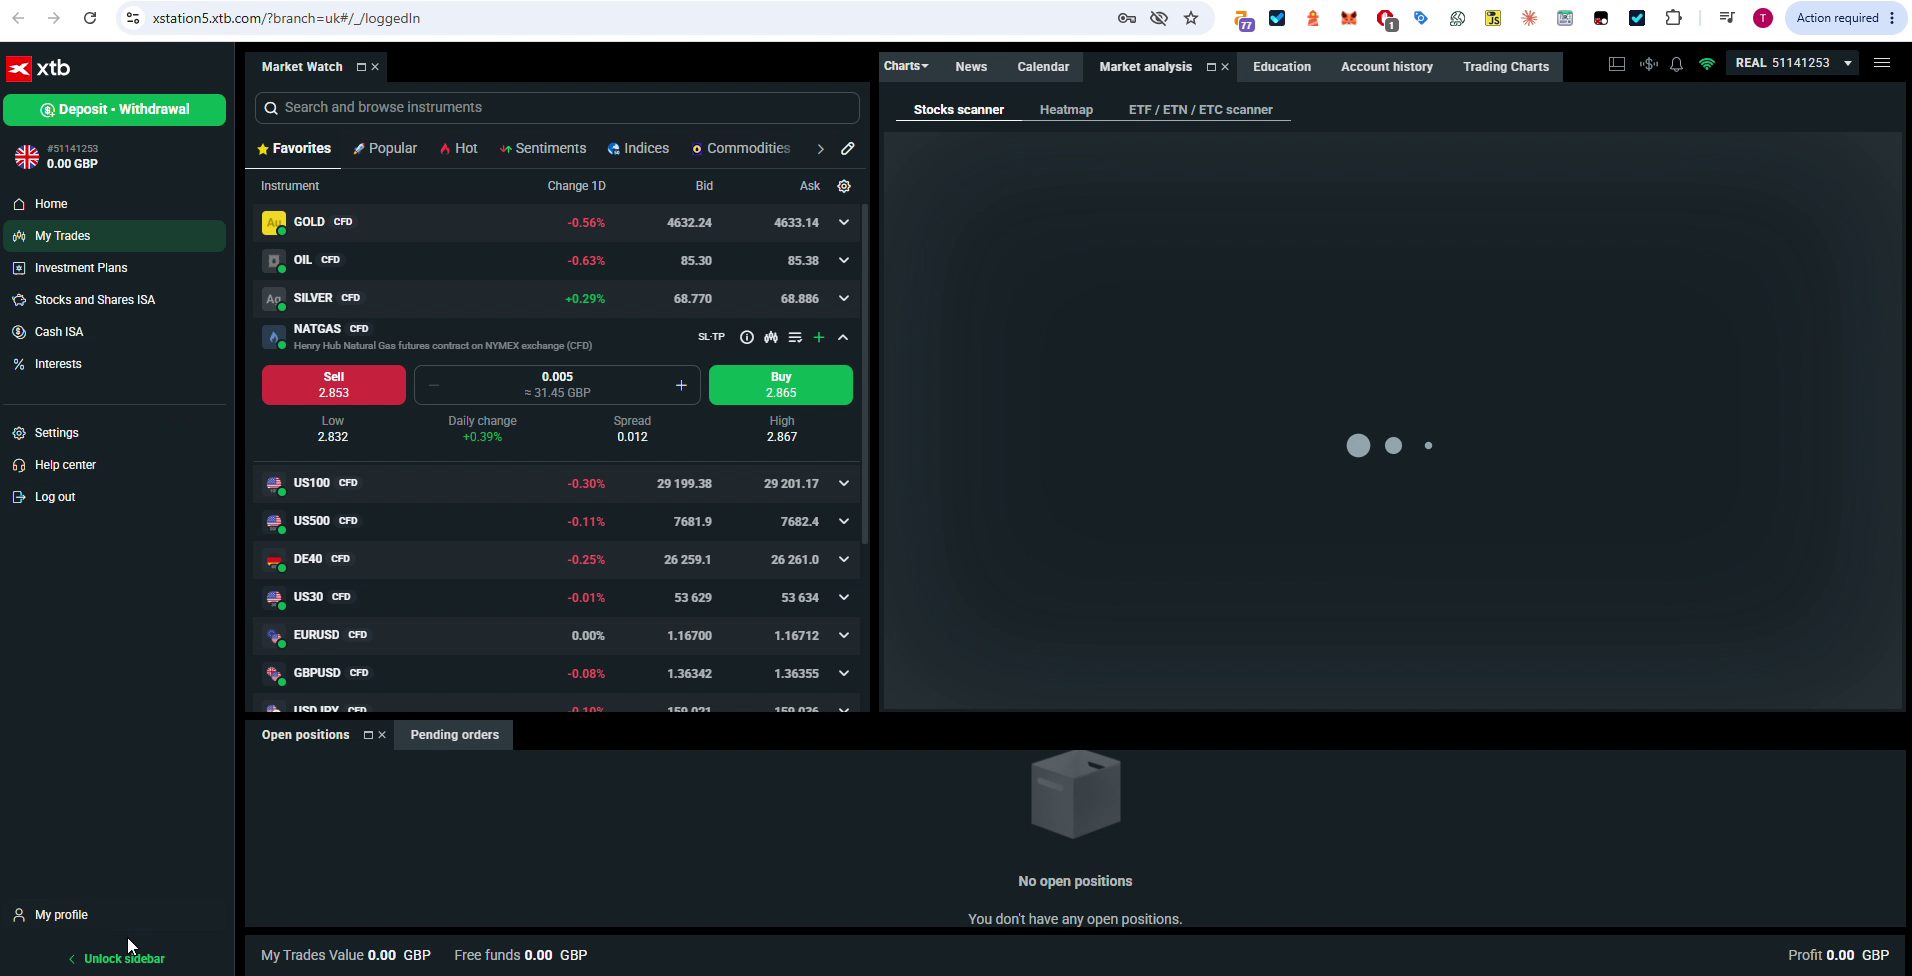
- Proprietary xStation 5 platform only, no MT4 or MT5
How Much Does It Cost to Invest with XTB?
XTB charges 0% commission on stocks and ETFs up to EUR 100,000 of monthly turnover, then 0.2% (min £10). There is no account, deposit or withdrawal fee, and no minimum deposit. Uninvested GBP funds earn 4% interest, calculated daily and paid monthly, and a 0.5% currency conversion cost applies on non-GBP stocks.
Is XTB Safe and FCA Regulated?
Yes, XTB is the trading name of X-Trade Brokers UK branch, FCA-authorised (FRN 522157), and client funds are protected under the FSCS. The broker has over 20 years on the market and 2.9 million clients worldwide.
Who Should Use XTB?
XTB suits long-term investors who want uninvested cash working at 4% interest while building a portfolio through fractional shares and auto-invest Investment Plans, inside a flexible Stocks and Shares ISA that lets withdrawals be reinvested in the same tax year without eating the £20,000 allowance.
What Features Stand Out on XTB's Platform?
Investment Plans automate ETF portfolio building with recurring payments, so compounding continues without manual reinvestment. Fractional investing opens the 9,100+ real stocks and ETFs to small contributions, and the flexible ISA structure supports tax-efficient long-term compounding.

Interactive Investor – Best for Long-Term Investors Focused on ISA and SIPP Compounding
- Fees & Spreads
- 3.9
- Platform & Tools
- 4.3
- Customer Service
- 3.8
- Ease of Use
- 4.2
- Mobile App
- 3.6
Pros
- Flat monthly fee structure
- Wide range of ISAs and SIPPs
- Excellent for long-term investors
- Strong research and tools
Cons
- Monthly fee may not suit small portfolios
- Interface less modern than competitors
- Trading fees on top of subscription
How Much Does It Cost to Invest with Interactive Investor?
Interactive Investor charges a flat monthly fee starting at £4.99/month (Investor plan). Trading costs £3.99 per UK trade. There are no percentage-based fees, making it cost-effective for larger portfolios.
Is Interactive Investor Safe and FCA Regulated?
Yes, Interactive Investor is FCA-regulated and client money is protected under FSCS up to £85,000. The platform is considered one of the most secure and reputable in the UK.
Who Should Use Interactive Investor?
Interactive Investor is ideal for serious, long-term investors who want flat-fee pricing, access to ISAs and SIPPs, and a wide selection of funds and ETFs.
What Features Stand Out on Interactive Investor's Platform?
The platform offers Quick-start funds, regular investing options, and comprehensive research tools. Users benefit from expert content, portfolio analysis, and a range of tax-efficient accounts.
Trading.com – Real Shares Alongside a CFD Account
- Fees & Spreads
- 4.2
- Platform & Tools
- 4.5
- Customer Service
- 3.8
- Ease of Use
- 4.1
- Mobile App
- 4.2
Pros
- FCA-regulated (FRN 705428) and FSCS-protected
- Commission-free Investment Account with real shares, alongside a separate CFD/forex account
- £10,000 demo account with no expiry to practise before committing funds
Cons
- Narrower published detail for ISA, interest-on-cash and Investment Account app features
- Younger UK track record than the other providers on this page
- Human support Monday to Friday only
How Much Does It Cost to Invest with Trading.com?
Trading.com runs a commission-free Investment Account for real shares alongside a separate leveraged CFD/forex account, both under one login. Its published Investment Account detail is less extensive than the other providers here, so check the current schedule directly when comparing ancillary fees.
Is Trading.com Safe and FCA Regulated?
Yes. Trading.com is the UK trading name of Trading.com Markets UK Limited, FCA-authorised since 2016 (FRN 705428), the rebranded UK arm of XM.
Who Should Use Trading.com?
Investors who want a simple, FCA-regulated home for real shares, with the option to try leveraged CFD/forex trading on the same login using a £10,000 no-expiry demo account first.
What Features Stand Out on Trading.com's Platform?
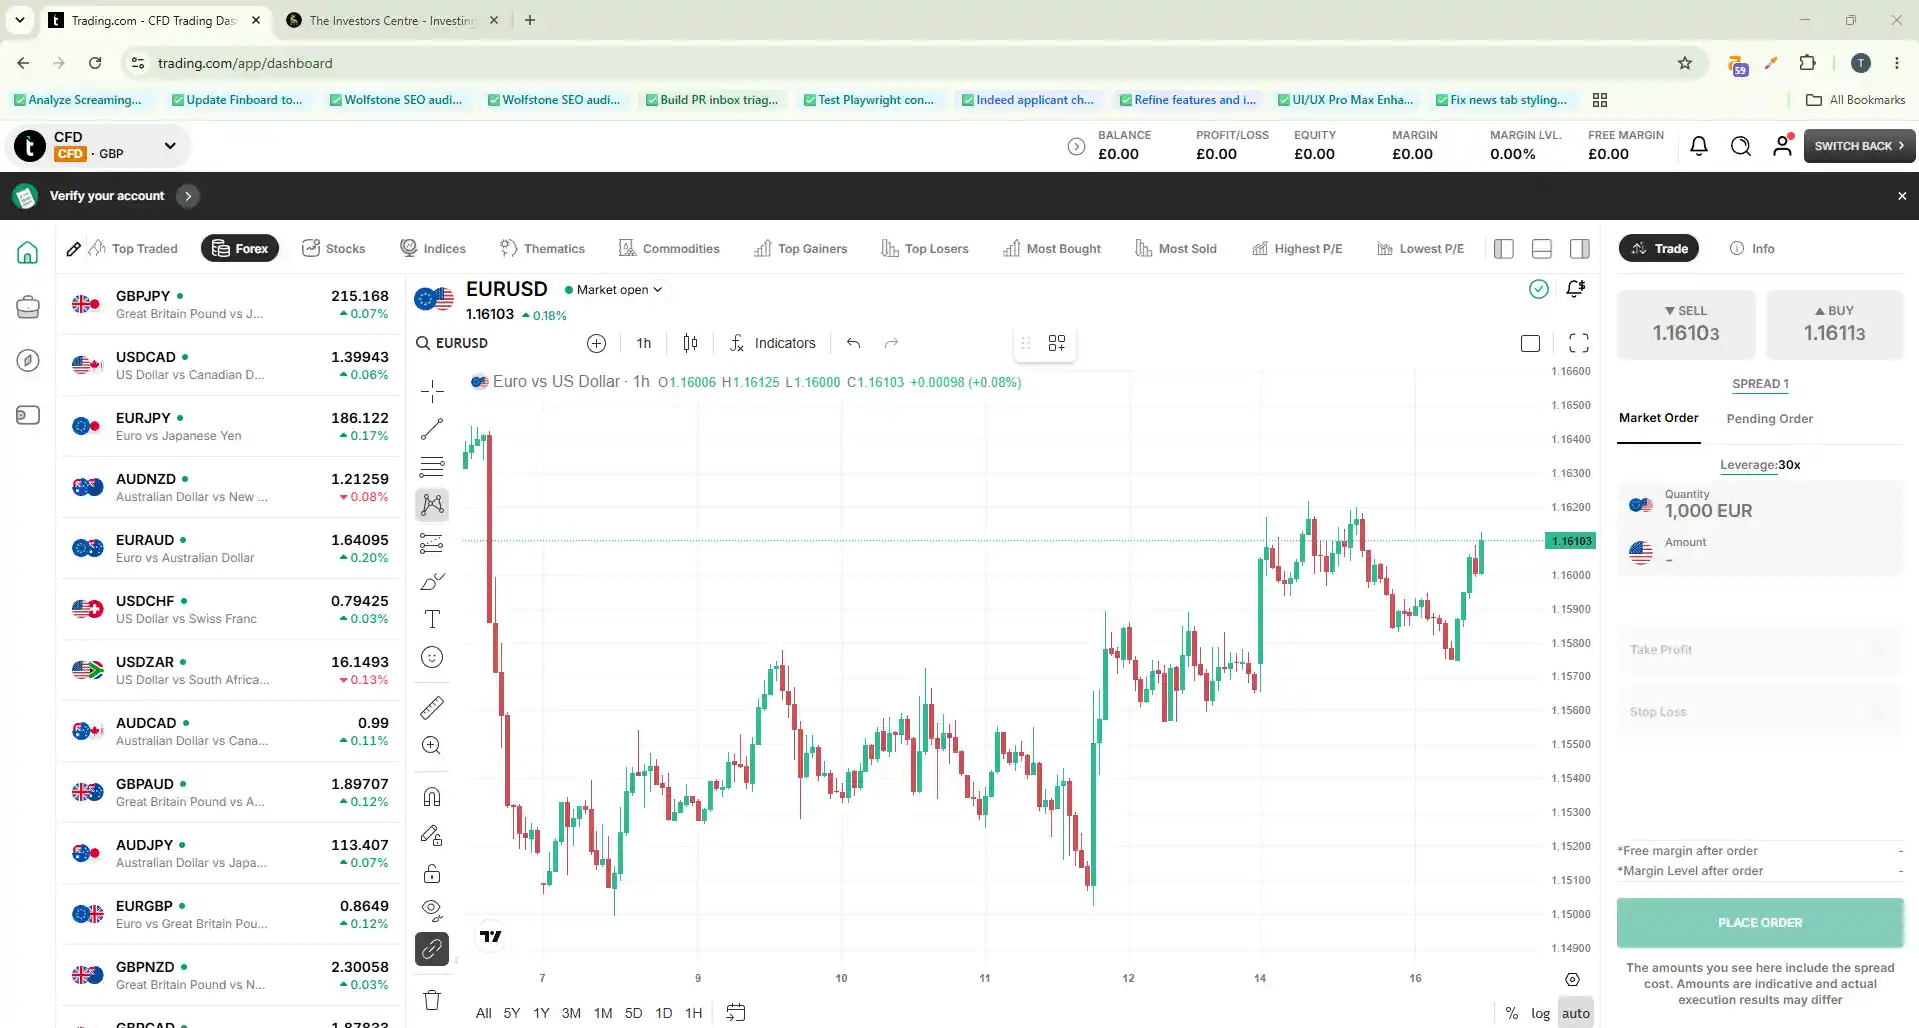
The commission-free Investment Account for real shares sits alongside a CFD/forex account with TradingView-powered charts and MetaTrader 5 connectivity, so a self-directed investor and a leveraged trader can use the same login for different goals.
Trading 212 – Best User Interface
- Fees & Spreads
- 4.3
- Platform & Tools
- 3.5
- Customer Service
- 3.6
- Ease of Use
- 4.4
- Mobile App
- 4.3
Pros
- Commission-free stocks and ETFs
- No platform or withdrawal fees
- Fractional shares available
- Interest on uninvested cash
Cons
- Limited research tools
- No ISA transfer in
- Currency conversion fees
How Much Does It Cost to Invest with Trading 212?
Trading 212 offers commission-free investing on UK and US stocks and ETFs. There are no platform, withdrawal, or inactivity fees*. Currency conversion fees apply for non-GBP trades.
Is Trading 212 Safe and FCA Regulated?
Yes, Trading 212 is regulated by the FCA and provides FSCS protection up to £85,000. It uses bank-level encryption and segregated accounts for user funds.
Who Should Use Trading 212?
Trading 212 suits beginners and cost-conscious investors who want a simple, modern app with no trading fees. It's also great for those building a portfolio gradually through fractional shares.
What Features Stand Out on Trading 212's Platform?
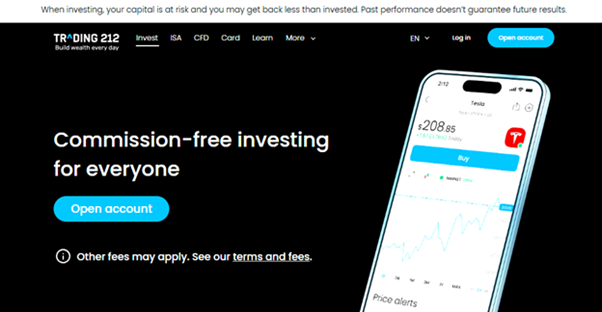
The app offers commission-free trading, AutoInvest pies, fractional shares, and competitive interest on cash. The interface is clean and intuitive, with real-time data and quick execution.
What do I need to know about Compound Interest?
What is compound interest and how does it work?
Compound interest means earning interest on both your initial investment and previous returns. Over time, this snowball effect accelerates growth. For UK investors, compounding applies to savings accounts, ISAs, pensions, and reinvested dividends, making time in the market more important than short-term gains.
Why is compound interest powerful for UK investors?
Compound interest builds wealth because growth accelerates the longer money stays invested. Even modest returns multiply significantly over decades. UK investors benefit most when they reinvest dividends and interest automatically, letting the compounding process magnify gains without needing to add large additional contributions.
How is compound interest different from simple interest?
Simple interest is calculated only on the initial amount, while compound interest applies to both the principal and accumulated returns. Over time, compounding delivers far larger growth. For UK savers and investors, this difference determines whether money simply keeps pace with inflation or outpaces it.
Compound Interest over Time
Compounding: Cash vs S&P 500 vs Inflation (1975–2025)
Assumes £10,000 starting balance and constant annual rates: Cash 2.5%, UK inflation 3%, S&P 500 total return 10% adjusted for inflation.
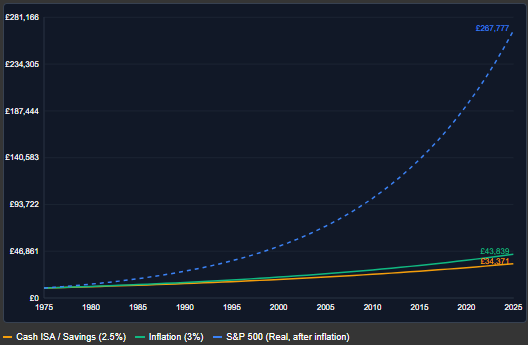
The chart compares £10,000 invested since 1975. Cash ISAs compounded at 2.5% but failed to keep pace with 3% inflation. The inflation-adjusted S&P 500 compounded at about 6.8% annually, showing significant real growth. It highlights why long-term equity exposure outperforms cash savings.
Compound Interest Calculator
Compound Interest Calculator
Calculate Your Investment Growth Over Time
Investment Details
Investment Projection
Enter investment details to see your projected returns
Investment Growth Over Time
Best Compound Interest Investments in the UK
What are my options as a UK investor?
UK investors can choose between fixed-rate savings products, such as Cash ISAs, or market-based investments like index funds, ETFs, REITs, and pensions. Fixed products provide certainty but weaker long-term growth. Market exposure typically outpaces inflation, delivering stronger compounded returns across decades.
Fixed Rate vs Market Investments
Fixed-rate accounts offer guaranteed but limited growth, often below inflation. Market investments carry risk but provide higher returns over time. Choosing between them depends on risk tolerance and goals. Long-term investors seeking real wealth growth usually benefit most from diversified, low-cost, market-based strategies.
Interest vs Inflation: Does Cash Keep Pace?
Cash accounts rarely beat inflation in the UK. Even at 3% annual interest, long-term inflation erodes purchasing power. By contrast, equity investments historically average higher returns, allowing compounding to build real wealth. For long-term growth, markets outperform cash, though savings remain useful for safety.
Which accounts support compound interest in the UK?
Accounts supporting compounding include Cash ISAs, Stocks & Shares ISAs, workplace pensions, and SIPPs. These accounts often allow reinvestment of interest or dividends. Tax efficiency further enhances compounding, particularly in ISAs and pensions, where gains are shielded from income and capital gains taxes.
How do Cash ISAs work for compounding?
Cash ISAs earn interest on deposits, with returns reinvested automatically. Compounding occurs annually or monthly, depending on the provider. While secure and tax-free, long-term returns usually lag inflation, limiting their effectiveness as a wealth-building vehicle compared to equity-based investments.
How often is interest compounded in an ISA?
Most UK banks compound ISA interest annually, though some accounts calculate monthly. The frequency matters less than the rate itself. Even with monthly compounding, low returns mean Cash ISAs often fail to protect long-term purchasing power against inflationary pressures.
Investment Types for Compound Growth
Are Stocks & Shares ISAs good for compound interest?
Yes. Stocks & Shares ISAs allow reinvestment of dividends and gains into funds, ETFs, or shares. Compounding works powerfully over decades, particularly with index funds. Returns are tax-free, making ISAs one of the most efficient long-term compounding vehicles for UK investors.
Can dividends be reinvested to create compounding?
Yes. Reinvesting dividends means each payout buys more shares, which then produce further dividends. Over time, this snowball effect significantly increases growth. Most UK platforms allow dividend reinvestment plans (DRIPs), which automate the process inside Stocks & Shares ISAs.
Why index funds are powerful for long-term growth
Index funds track markets cheaply, spreading risk across hundreds of companies. By reinvesting dividends, investors benefit from market-wide compounding at minimal cost. In a Stocks & Shares ISA, this approach grows wealth tax-free, historically outperforming inflation and fixed-rate accounts over decades.
Are REITs a good compound interest investment?
REITs pay dividends from property income, which can be reinvested. They offer diversification into real estate and regular income streams. However, they carry market risk, are sensitive to interest rates, and may be more volatile than other compounding investment choices.
Do REITs pay dividends that can be reinvested?
Yes. REITs must distribute most income as dividends. Investors can reinvest these payouts, creating compounding growth over time. Many UK platforms support automatic reinvestment through dividend plans, helping build exposure to property markets without directly owning physical assets.
What are the risks of compounding through property funds?
REITs can be volatile during downturns, as property values and rental income fluctuate. Rising interest rates may reduce profitability. While dividends support compounding, risks make REITs better suited as part of a diversified portfolio, not as a sole compounding vehicle.
Can ETFs provide compound interest returns?
Yes. Dividend-paying ETFs reinvest or distribute income. By reinvesting, compounding accelerates growth. ETFs track global or UK indices, offering broad diversification at low cost. Over decades, ETF compounding typically outpaces inflation, especially when held tax-efficiently in an ISA or pension.
How do dividend-paying ETFs enable compounding?
Dividend-paying ETFs distribute earnings from their underlying holdings. Reinvested dividends buy more ETF units, which generate further income. Over time, this cycle compounds returns, amplifying wealth growth compared to simply holding the ETF without reinvestment.
Are global ETFs better than UK-only options for compounding?
Global ETFs spread risk across markets and sectors, often delivering stronger compounding by capturing worldwide growth. UK-only ETFs may limit exposure to higher-growth regions. For most investors, global diversification improves long-term compounding while reducing reliance on a single market's performance.
Can bonds and gilts provide compound interest?
Yes, though growth is modest. Bonds and gilts pay interest, which can be reinvested to generate compounding. Returns are typically lower than equities but provide stability. They are often used as part of diversified portfolios to balance risk and support steadier growth.
What about corporate bonds with reinvested coupons?
Corporate bonds often offer higher yields than government gilts. Reinvesting coupon payments allows compounding over time. However, credit risk and defaults are considerations. Corporate bonds can add diversification and enhance compounding when balanced with equities in a long-term portfolio.
Are pension accounts (SIPPs, workplace pensions) compound interest investments?
Yes. Pensions benefit from long-term compounding of contributions, investment growth, and reinvested dividends. Tax relief and employer contributions accelerate growth further. SIPPs and workplace pensions are among the most effective ways for UK investors to harness compounding over decades.
How does compounding work inside a pension account?
Pension contributions are invested in funds that generate returns. Reinvested dividends and capital growth compound over time. Tax relief boosts contributions upfront, making pensions especially powerful for long-term compounding, provided investors remain invested consistently.
What role does employer contribution play in compounding?
Employer contributions significantly increase pension growth. Combined with tax relief, they create a compounding effect on both contributions and returns. Over decades, this triple boost makes pensions one of the strongest wealth-building vehicles for UK investors.

Strategies to Maximise Compound Interest
How long should you invest for to benefit from compounding?
The longer you stay invested, the more powerful compounding becomes. Over 20–30 years, even modest annual returns multiply significantly. Short-term investments rarely capture the full benefits, making long-term consistency essential for maximising compounded growth.
How much difference does starting early make?
Starting early drastically improves results. A small monthly investment begun in your twenties compounds into far greater wealth than larger contributions begun later. Time is the most critical factor, outweighing short-term market fluctuations or small changes in contributions. Starting late with a larger lump sum changes the maths rather than ending it. One of the most common late lump sums is the money freed by selling a bigger home, and we have run those numbers in downsizing to fund retirement.
Should you reinvest dividends and interest automatically?
Yes. Reinvesting dividends and interest ensures compounding occurs seamlessly. Automatic reinvestment eliminates missed opportunities and accelerates long-term growth. UK investors should opt for dividend reinvestment plans in ISAs and pensions to maximise efficiency and consistency.
How do fees and taxes affect compound returns?
High fees erode compounding by reducing the base on which returns grow. Taxes on gains or dividends further weaken growth. Using tax-efficient accounts such as ISAs and pensions, combined with low-cost funds, preserves more of the compounding effect over time.
Risks of Compound Interest Investments
Are all compound interest investments safe?
No. Cash ISAs are safe but deliver low returns. Market investments carry risk, including volatility and capital loss. Diversification, time in the market, and using tax-efficient accounts reduce risk, but investors must balance safety with the need to outpace inflation.
Can inflation reduce the effect of compounding?
Yes. Inflation erodes purchasing power, reducing the real value of compounded returns. Cash investments rarely keep pace, making equities and diversified funds more effective long-term. Beating inflation is crucial for compound interest to build real wealth.
What are the risks of compounding in stock-based investments?
Market downturns can reduce portfolio value, slowing compounding. Dividends may be cut, and short-term losses occur. However, over long horizons, diversified stock investments historically recover and deliver compounding that outpaces inflation, provided investors stay disciplined and invested.
Final Thoughts
Compound interest is most powerful when combined with time, reinvestment, and tax efficiency. While cash savings provide security, they rarely beat inflation. For long-term UK investors, Stocks & Shares ISAs with index funds, pensions, and ETFs offer the strongest compounded growth, building wealth steadily across decades.
- Stocks & Shares ISAs with Global Index Funds – Tax-free growth, dividend reinvestment, and diversification make this the most effective compounding vehicle.
- Workplace Pensions and SIPPs – Employer contributions plus tax relief amplify compounding for retirement savings.
- Dividend-Paying ETFs – Low-cost global exposure with automatic reinvestment supports long-term compounding.
- REITs in an ISA – Regular property income reinvested can compound steadily, though more volatile.
- Government and Corporate Bonds – Lower growth but stability, useful alongside equities to balance compounding strategies.
Discuss UK Compound Interest Investments
Targeting compound interest growth? Share your wrapper choice (ISA / pension / GIA), allocation, and the rate you're actually realising after fees. Our community earns Equity for quality contributions.
Discussion 0 comments
Be the first to start discussing this topic! Log in or create an account to share your thoughts.
Log In Create AccountFAQs
References
- GOV.UK – Individual Savings Accounts (ISAs)
- MoneyHelper – Compound Interest Explained
- Bank of England – How Interest Rates Affect You
- Vanguard UK – Investing for the Long Term
- Hargreaves Lansdown – What is a SIPP?
No comments yet. Be the first to start discussing this topic!